Making the Case for (Some) Engineered Indices
Ever since the advent of indexed crediting in insurance products, one crediting strategy has ruled them all – the S&P 500 annual point-to-point with a cap. There are now more than 200 indices available in FIA products. There are at least two dozen distinct crediting strategies over crediting terms ranging from 1 year to 6 years. If you multiply all of that up, there are around 35,000 possible indexed crediting strategies based solely on the ingredients in market today. And yet, something like 60% of premium flows in FIA still go to the S&P 500 annual point-to-point with a cap. It is the default strategy against which all other strategies are compared.
That’s not good news for all of the other options, particularly the once-revered and now-reviled category of “engineered” indices that are specifically designed for use in insurance products. When these indices started to proliferate a decade ago, they were positioned as a more sophisticated way to get exposure to more upside potential across a wide range of asset classes in one nice, neat, well branded, flawlessly backtested and relentlessly promoted package. Expectations for performance were incredibly high – and, by and large, the indices didn’t live up to them.
The situation has become so challenging that many carriers are removing older, poorly performing indices from existing products and replacing them with newer variants. Allianz has evolved its Bloomberg US Dynamic Balance Index to now the 3rd iteration, which looks almost nothing like the original. Nationwide removed JP Morgan Mozaic, which arguably kicked off the entire engineered index craze, from its flagship New Heights product. Athene has made similar moves with older indices. There is, it seems, a shelf life for these things.
Advisors are understandably dismayed, frustrated and distrusting of any new index posited as a solution to past problems. Higher interest rates have made switching allocations back to the S&P 500 with a cap an easy choice. But in doing so, they’re also making another choice – they’re choosing a particular index with a particular index participation lever that has some particular (and peculiar) performance characteristics.
A cap may be familiar, but that doesn’t mean it’s the best option for the client. All indexed crediting strategies have tradeoffs. There’s a case to be made for caps, but there’s also a case to be made for participation rates – and yes, even some engineered indices. To understand why someone might choose an engineered index, we actually have to start back at the beginning by take a new look at the most familiar strategy, the annual S&P 500 point-to-point with a cap.
The reasons for its universal availability and persistent popularity are not hard to spot. The S&P 500 is the most widely recognized large cap equity benchmark for the US domestic market. Most people think of equity returns over one-year time horizons, so it follows that the most popular indexed crediting strategy also has a one-year crediting term. Point-to-point is the most straightforward way to calculate gains in an index over a period of time. In a word, calculating S&P 500 returns on an annual basis using a point-to-point methodology is simple. And simple is what consumers and agents want.
Where things get interesting is the fact that the cap is the preferred choice of providing exposure to the underlying index. All consumers would, of course, love to have a 0% crediting floor with full upside participation in index returns, but that’s not possible in most economic environments. Each carrier offers index participation by purchasing options. It sets the participation in the index by aligning the cost of the option with the yield that is coming from the portfolio of assets supporting the product, commonly called the “option budget.” The cost to provide full upside participation in the S&P 500 with no downside risk is far higher than the option budget. As a result, the carrier has to throttle the upside with some sort of limit.
The simplest form of limit is to set a participation rate that is less than 100%. If the participation rate is 60% and the index return is 12%, then the credit to the policyholder is 7.2%. Easy enough. If simplicity is what consumers and advisors want, then why isn’t everyone using participation rates instead of caps? Because participation rates have a tradeoff. They’re simple, but they’re also volatile.
Participation rates require the carrier to purchase an option at the starting index level, referred to as an at-the-money option. The price for those options is contingent on interest rates and the volatility of the index (the S&P 500, in this case). When volatility is low, the price of the option is low, which means that the carrier can offer a higher participation rate for a given available yield coming from the assets supporting the policy, often referred to as the “option budget”. When volatility spikes, the price of the option also spikes, which drives down the participation rate. The swings can be huge. In highly volatile years like 2008 and 2020, participation rates can go from something like 55% to 15% in the space of just a few days. That’s a bitter pill for folks to swallow if, like the vast majority of humanity, they’re not intimately familiar with option pricing dynamics.
As much as producers and consumers want simplicity, they also want something else – consistency. And that’s where a cap starts to enter the picture. Cap rates are inherently more consistent than participation rates. A cap provides full participation in the index between two boundaries – the floor, which is usually 0%, and the cap, which is set by the carrier on a periodic basis. The two boundaries each require their own separate options. To provide index participation upwards from the floor, the carrier purchases an at-the-money option for the full amount of the account value. To match the cost of hedging with the available option budget, the carrier sells an out-of-the-money option at the cap rate. In short, creating a cap involves two offsetting options rather than a single option.
As a result, the price of a cap is much more consistent because changes in volatility affect both the option purchased at the floor and sold at the cap. If volatility spikes, the carrier pays more for the option it’s buying, but also receives more for the option it’s selling. The net price is what matters, not the individual option prices themselves. The graph below assumes a constant 5% option budget for both cap and participation rate strategies. Rather than showing the rates themselves, it shows the difference between the average rate over the past 10 years and the rate on any given day. As you can see, participation rates swing far more quickly and far more dramatically than cap rates.
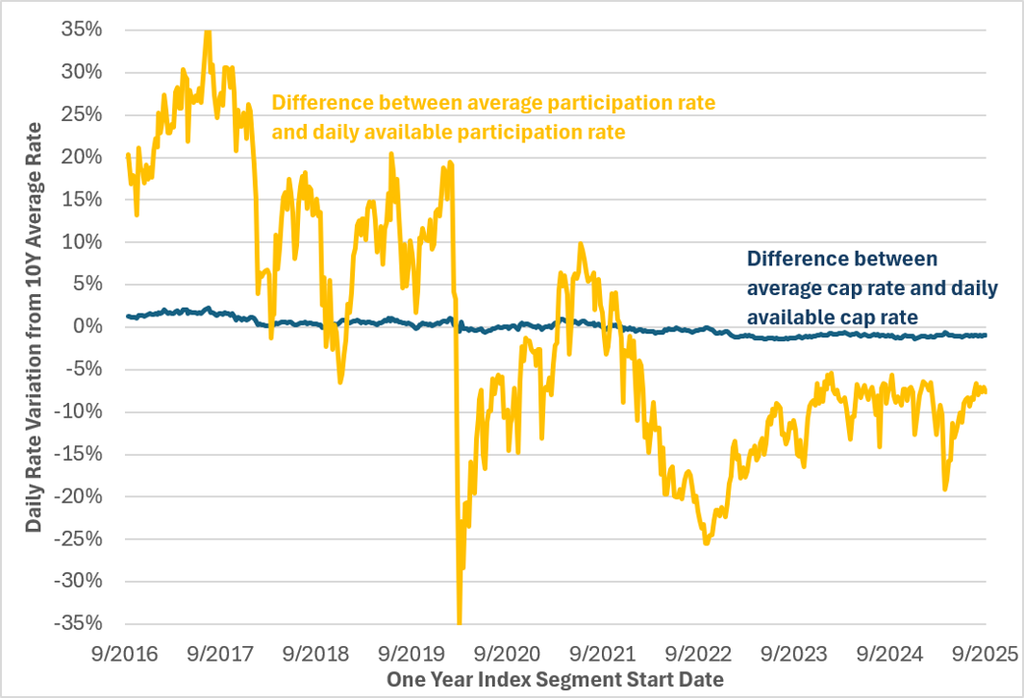
This comparison sets up an interesting question – which one is better? That depends on what you want. If you want simplicity and pure performance, then the participation rate is the way to go, as we discussed in our white paper two years ago, but participation rates have more variability. Caps are inherently more consistent because the two option prices offset each other, muting the effect of volatility. If it’s important for future rates to be as consistent as possible with the initial rate, then the cap is a better choice.
However, there’s a cost. The S&P 500 delivers annual returns above a 10% cap approximately 50% of the time and the average foregone return in those scenarios is around 20%. Choosing a cap leaves a lot of index performance on the table – that’s the cost of rate consistency, and you can actually see it play out in historical performance data.
The chart below compares crediting performance each week since 2016 for both strategies. The cap is held at 10% and the participation rate is calibrated using the same market cost as the 10% cap at that time, which makes it a fair comparison even though option prices for both strategies changed throughout the period. Over the full period, the participation rate strategy outperforms the cap strategy by an average of nearly 2% on an annualized return basis.
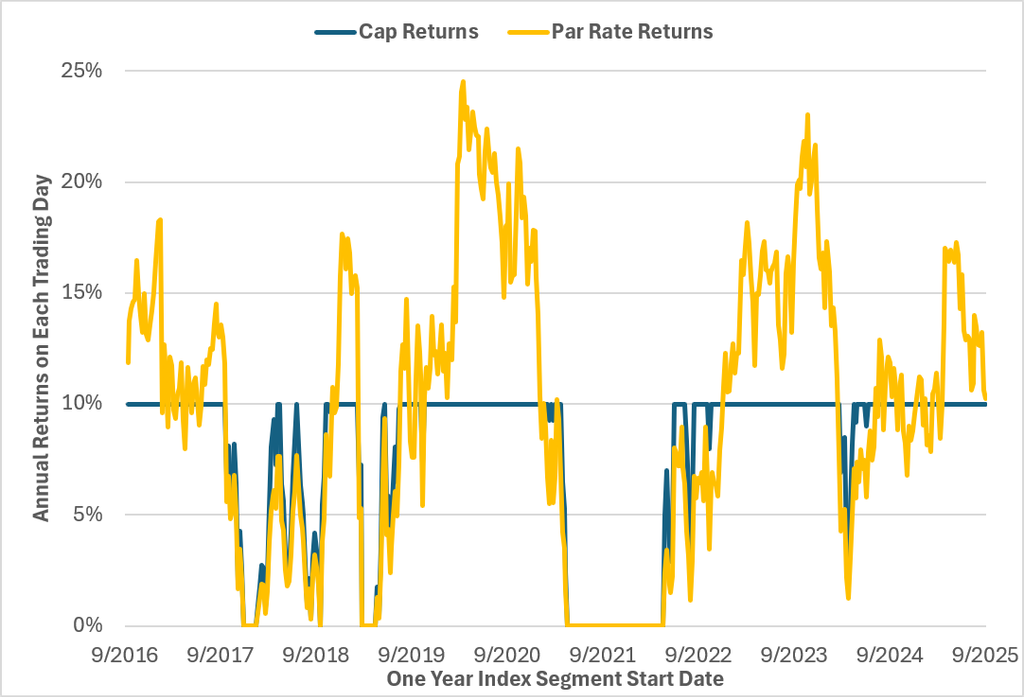
The story, then, is pretty simple. Producers and clients gravitate towards cap strategies because the caps are more stable and consistent – and also because, in the minds of many advisors and consumers, an average S&P 500 return of 8% seems like it would be fully captured by a cap strategy. In reality, annual S&P 500 returns often exceed the cap. Choosing the rate stability of a cap means missing out on the upside performance potential of a highly variable participation rate. That’s the fundamental tradeoff between the two strategies.
As wonky as option pricing dynamics can feel, the reality is that this is just a different form of the classic risk/return investing tradeoff. Here, risk doesn’t mean loss, because both strategies have the same loss-mitigating floor at 0%. Risk means variability of the rate offered by the carrier. If you’re willing to take more risk, then you’ll get rewarded over the long-term with higher returns. Rather than just defaulting to the cap, advisors should consider framing the choice as simply a tradeoff. Some clients want consistency. Some clients want performance. Fortunately, they have the ability to make the choice in most modern FIA products.
Yet what if there was a way to get the best of both worlds – rate stability and uncapped upside? That’s what an engineered index with a volatility control mechanism can offer. The construction of these indices can be very complex, but the logic behind them is very simple. Volatility is the primary driver of option prices. If the index itself can maintain a continuous volatility profile, then the price of the options will be stable. Stable option prices mean that the carrier can also offer stable participation rates. Tame the volatility of the index and you tame the option prices – and, by extension, you tame the participation rates. As a result, we should expect the participation rates for engineered indices to stay largely static over the term of the contract.
Strictly speaking, there is no pure economic advantage to stable participation rates or caps over the term of an FIA contract. If anything, as we’ve shown, rate stability usually comes at the cost of performance. So why do producers and their clients seem to put rate stability above all else? Because it’s the only optical metric that can be used to gauge whether the insurer is setting “fair” renewal rates. The problem is that, as any parent knows, fair isn’t equal.
Fairness in the context of setting rates in FIA products means that the carrier is spending the full available option budget for the policyholder. Participation rates will change continuously even while remaining fair. Cap rates can change as well and often do. The fact that participation rates for engineered indices don’t change doesn’t mean that they’re more or less fair to the policyholder. The actual participation rate or cap rates themselves are largely irrelevant.
That’s the pure theory. In the real world, producers and clients can’t see what the carrier is spending behind the scenes. They don’t have a way to gauge what’s “fair.” Until carriers offer more transparency to their rate setting processes, producers and clients will continue to rely on the consistency of participation rates and cap rates as the next best gauge of fairness. And on that score, engineered indices offer a way to know for certain if a carrier is playing fair or not, because the dynamic nature of the index itself allows for inherent stability of option prices and, therefore, participation rates over the term of an FIA.
Of course, there’s a tradeoff. How does the index volatility get tamed? By over-investing when index volatility is lower than the volatility target and under-investing when index volatility is higher than the volatility target. Volatility control sounds complex, though in reality it’s an incredibly simple mechanism. The volatility-controlled index continuously adjusts its exposure to the underlying non-volatility-controlled index, such as the S&P 500, in order to maintain the target volatility. Sound familiar? It’s the same concept as a traditional participation rate, only this time the participation rate is dynamically changing inside of the index itself. We can call it the level of index exposure.
To demonstrate how this works, we created a simple volatility-controlled variant of the S&P 500, which we’ll call the Annuity Edge 12%. Every day, it looks back over the past 30 trading days of S&P 500 returns to determine the actual volatility of the index. The Annuity Edge 12% index then adjusts its exposure based on the ratio of actual S&P 500 volatility to the 12% volatility target. If the S&P 500 volatility is above the target, the exposure falls below 100%. If it’s below the target, the exposure goes above 100%. It’s as simple as that. Because the rebalancing happens every day, the exposure to the S&P 500 within the Annuity Edge 12% also changes every day. Take a look at the level of index exposure over the past 10 years:
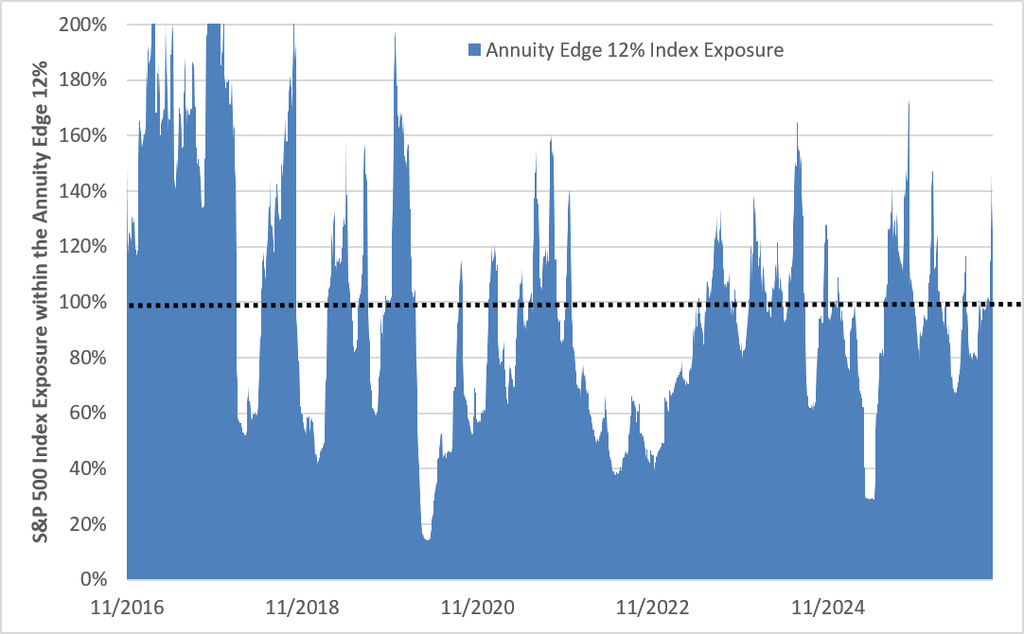
The defining characteristic of this chart is constant change. This index reacts every single day to each 30-day volatility reading and it can move dramatically in the space of a week or even a day. It is even more variable than using a pure participation rate strategy for the simple reason that the index recalibrates every day based on 30-day past volatility, whereas the participation rate recalibrates every year based on one year forward expected (also called implied) volatility. The volatility profile of the S&P 500 is far more stable over a one-year time horizon than over a 30-day time horizon. Take a look at the available participation rate for the S&P 500 shown in yellow relative to the index exposure in the Annuity Edge 12% index shown in blue:
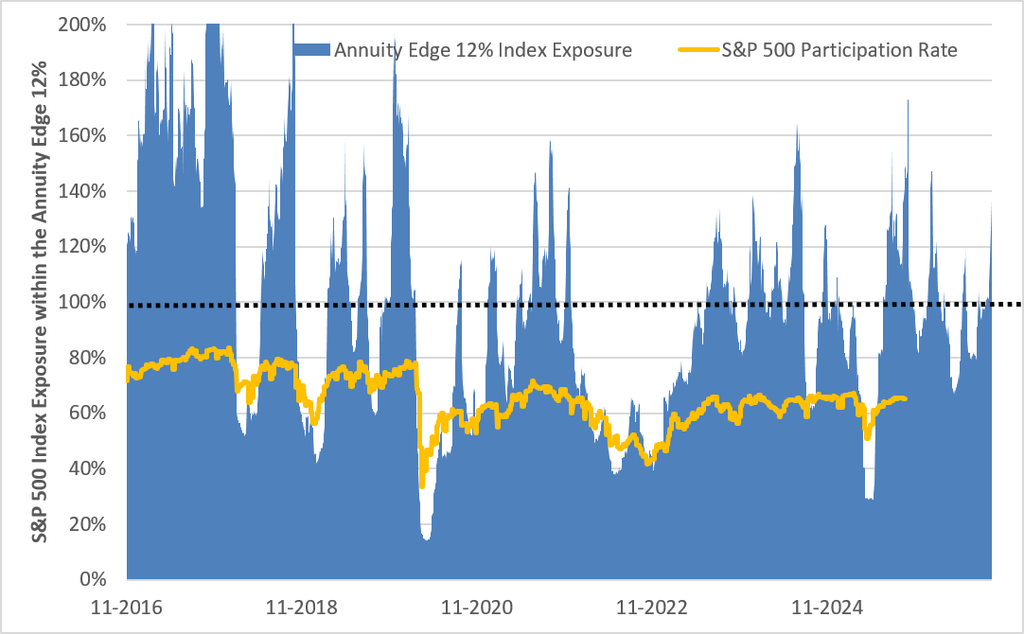
So, what do you get for all this extra variability? If the performance of a participation rate is higher than a cap because participation rates are more variable than cap rates, then it would stand to reason that a volatility-controlled S&P 500-based index with more index exposure variability than a traditional S&P 500 participation rate would also deliver higher performance. That’s particularly true if the index deducts the risk-free rate from the index return calculation, which eliminates the effect of interest rates on the price of the options while creating a hurdle that the index has to clear in order to deliver returns. That hurdle rate can change, creating more variability – yet also cheaper options with higher participation rates and, therefore, more potential upside.
No surprise, we see outperformance playing out in the data. The chart below shows annual returns for all three options on a daily basis starting on 1/1/2017. The participation rates on both the S&P 500 and the Annuity Edge 12% change daily to match the cost of a 10% cap on the same day. That allows the cap to stay constant, which is how most producers and clients want to experience their FIA performance.
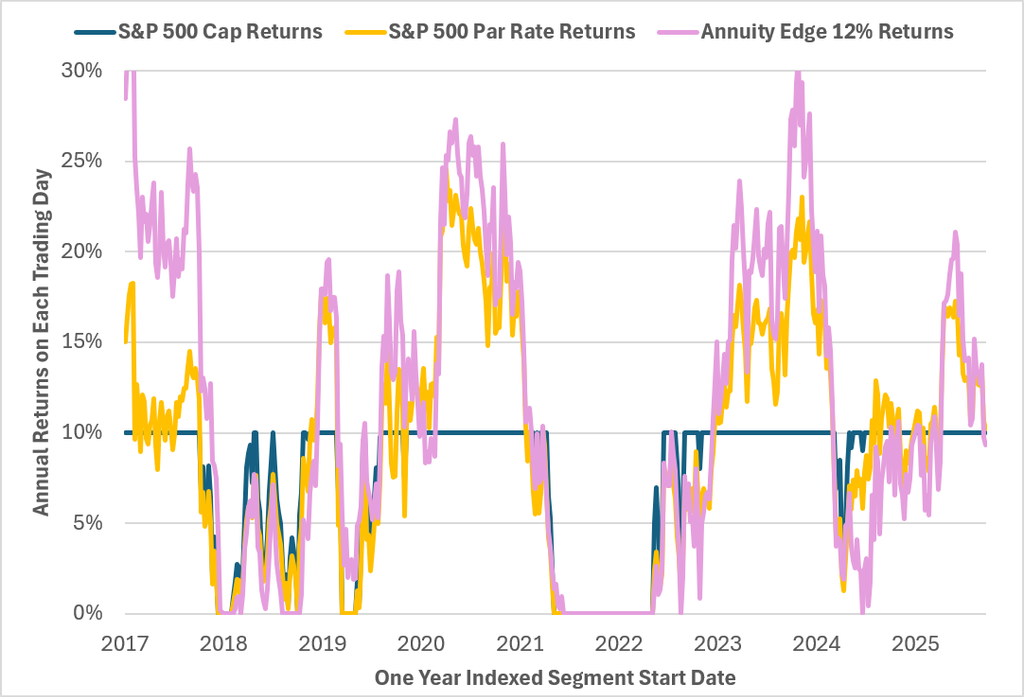
The average annual credit calculated each day for the cap strategy is 7.62%. The average for the participation rate is 9.48%. Meanwhile, the Annuity Edge 12% blows them both away with an average annual credit of 11.29%. And remember – this isn’t some weird, backtest-optimized structure. The Annuity Edge 12% index is literally just rebalancing its exposure to the S&P 500 on a daily basis and deducting the risk-free rate. That’s all it’s doing. And yet in doing so, it’s the most variable of the options and, therefore, it should deliver the highest performance over the long run – as long as the underlying index performs in excess of the risk-free rate hurdle.
What it will not do, however, is perfectly track the S&P 500. There are scenarios where high interest rates create a high enough hurdle rate that the index can’t clear it. That’s easy to spot in years where returns are modest. The more nuanced issue is that the volatility control mechanism’s 30-day lookback will result in real differences in performance. Case in point – 2025. The S&P 500 whipsawed in April with the tariff announcements, dropping swiftly and then recovering quickly. As a result, the Annuity Edge 12% backed off of its S&P 500 index exposure for a couple of months while volatility normalized. At the same time, those months turned out to be some of the best of the year. As a result, the credits in the Annuity Edge 12% lag credits in the S&P 500 with a participation rate. Take a look at how buckets beginning in 2024 and stretching into 2025 would have performed.
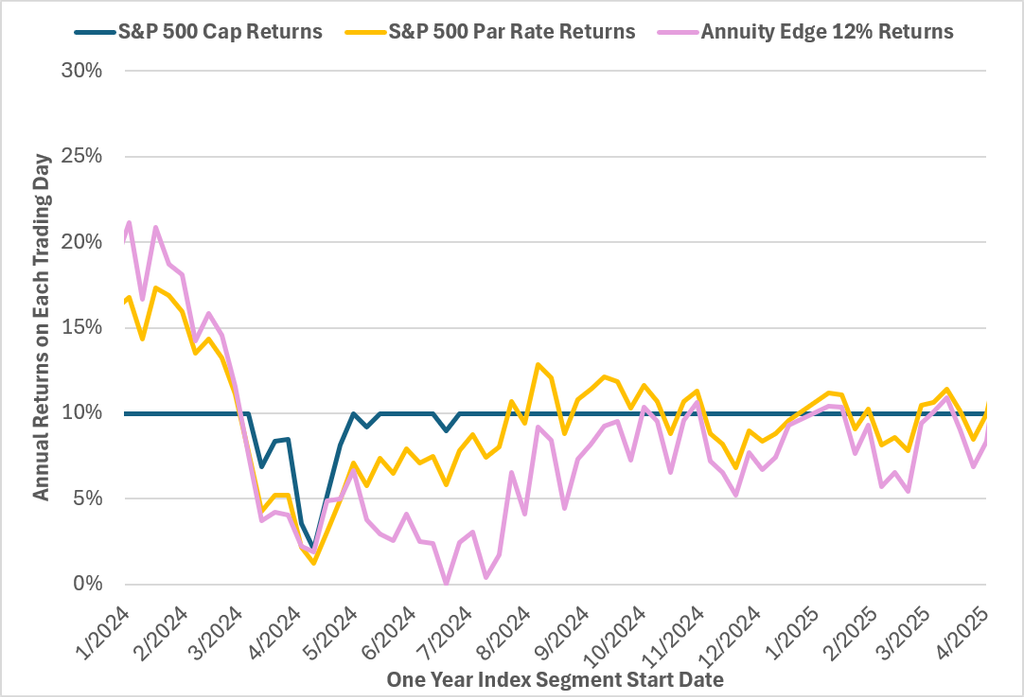
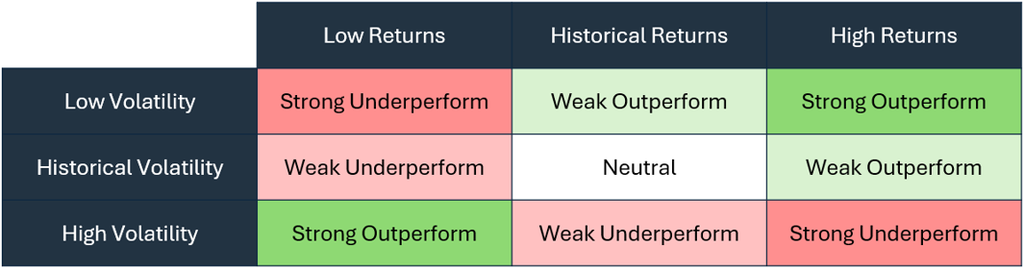
We saw the same dynamic play out for almost every engineered index on the market. The reaction from advisors was understandable – they viewed it as a betrayal and one more example of where engineered indices had failed to live up to their premise. In reality, they’re doing exactly what they’re supposed to do. They’re inherently more variable. Most of the time, that variability delivers performance benefits. Sometimes, though, that variability can result in lagging returns, particularly in scenarios with both high index volatility and high index returns. When that happens, you can be sure that an engineered index will lag the S&P 500.
Conversely, in “normal” environments where volatility is modest and returns are strong, a simple index like Annuity Edge 12% will track its underlying index while delivering greater exposure and higher potential performance over the long term. The correlation coefficient for indexed credits over the past 10 years between the Annuity Edge 12% with a participation rate and the S&P 500 with a participation rate is 91.5%. In the grand scheme of financial assets, that is an incredibly high degree of correlation.
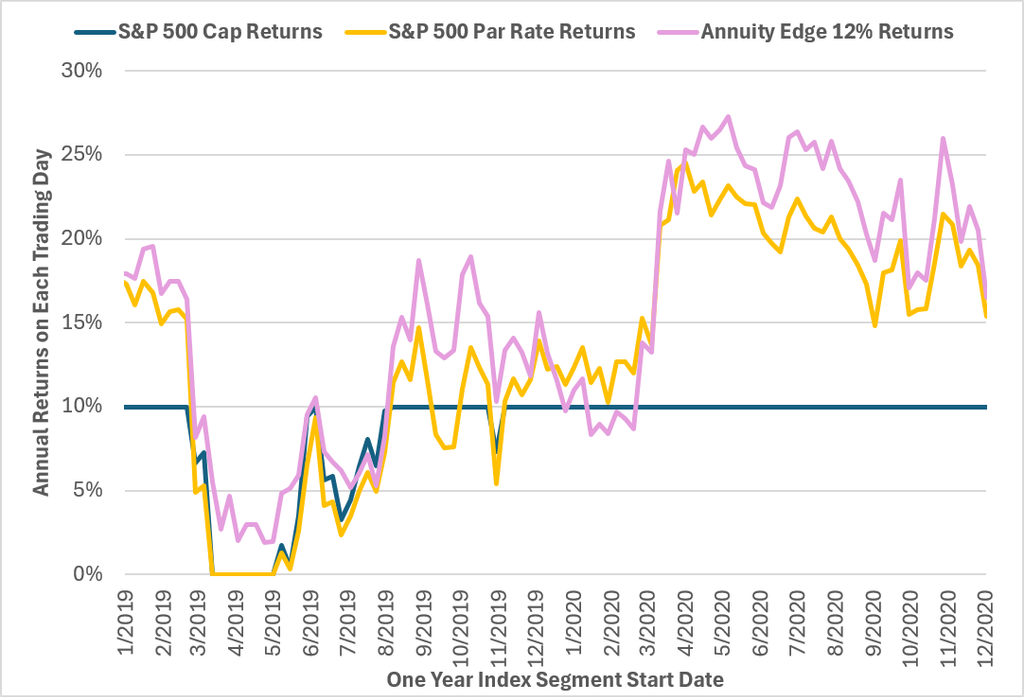
More importantly, we know exactly when and why the other 8.5% of non-correlation exists. When volatility is high, the correlation is going to break down – and that can be a good thing if S&P 500 returns are negative or a bad thing if S&P 500 returns are positive. For index terms starting in 2024, low correlation was a bad thing because returns were strong. By contrast, for index terms starting in 2019 and stretching into 2020, the volatility control mechanism in the Annuity Edge 12% actually protected some of those index terms from 0% credits by blunting some of the effects of the fall in the S&P 500 – while still preserving exposure during the recovery. For terms starting in 2019, non-correlation was a material benefit.
Advisors are skeptical of engineered indices – and for good reason. Engineered indices are often marketed as delivering huge backtested returns that result in double-digit illustrated performance that hasn’t come to pass in the real world. Engineered indices sometimes do unpredictable things because of embedded reallocation signals or the performance of some small allocation sleeve buried in the asset base of the index. Engineered indices can also have hidden fees paid to the banks, asset managers and sometimes third-party distribution firms that directly affect their ability to perform for customers. There have been a lot of assurances bordering on promises in engineered indices and very few of them have lived up to them with actual performance.
In its simplest form, without all the noise of various asset classes and proprietary allocation algorithms or specialized signaling structures, a volatility-controlled index allows the customer to make a very simple trade – more variability in index exposure in exchange for higher performance potential. It’s the same trade as choosing an S&P 500 participation rate over an S&P 500 cap. The degree to which a volatility-controlled index built on the S&P 500 can deliver higher performance depends on the relationship of volatility and returns. The chart below shows the 9 generic outcomes of performance for a basic volatility-controlled index:
For customers and agents, the question is simple – which one do you want, rate stability or performance? Caps offer the most rate stability but the lowest performance. Participation rates offer less rate stability but have higher performance. Volatility-controlled indices have even higher performance potential, but with performance that won’t necessarily track the S&P 500 in high volatility environments due to continuous changes to underlying index exposure. There is no right or wrong answer. There are only tradeoffs.
If advisors are going to recommend a volatility-controlled index alongside traditional S&P 500 allocations, they need to have confidence that the volatility-controlled index is going to do what it’s supposed to do over time relative to the S&P 500. In this context, that means continuously rebalancing index exposure to deliver performance similar to the S&P 500 when volatility is tame and temporarily deviating from the S&P 500 when volatility is high. That’s the behavior you’d expect from a volatility control mechanism layered on top of the S&P 500, with the benefit being a high and stable participation rate that drives better performance over the long term.
However, that’s not always what we see from engineered indices, even from those that are theoretically designed to be “simple” alternatives to the S&P 500. The reason why is not hard to deduce. Accounts in FIA products are often compared on the basis of illustrated performance, which incorporates historical performance data. Adding extra calculation components, such as momentum-based reallocation signals, can boost backtested performance. As a result, the FIA space has seen a proliferation of indices positioned as alternatives to the S&P 500 but with massive outperformance on the illustration due to additional index elements that aren’t always obvious.
The problem with outperformance on the illustration is that it rarely translates to outperformance in the real world. Tuning an index to perform well over the past 10 years means that the index will likely underperform in the next 10 years if the macroeconomic trends and conditions of the past don’t extend into the future. If the goal of a volatility-controlled index is to deliver dynamic daily exposure to the S&P 500 with stable participation rates and performance that broadly correlates to the S&P 500, then you don’t want underperformance or outperformance on the illustration. Large deviations in either direction are a warning sign that there’s more complexity in the index than meets the eye.
Fortunately, there are some families of volatility-controlled, engineered indices that fit the bill, delivering on the fundamental value proposition of a simple, S&P 500-derived index with volatility control designed to largely track the S&P 500 but with more potential upside participation than a traditional cap and participation rate. If you are positioning volatility-controlled indices as simply an extension of the crediting spectrum for the S&P 500, then these are the ones worth a look.
S&P 500 Daily Risk Control Series
Available at 5%, 7.5%, 10%, 12%, 15% and 18% on Total and Excess Return
This is the original volatility-controlled series released on the S&P 500. It debuted in 2009, which means we have more than 17 years of live performance. It uses a simple volatility control mechanism that tracks realized volatility on a daily basis, while it only rebalances index exposure once a month. Rebalancing more frequently isn’t necessarily a benefit or a cost – it just means that the index is slow to respond to volatility changes, which means there are times where the index has volatility meaningfully above or below its target, depending on what volatility in the S&P 500 is doing. As a result, options on Daily Risk Control indices tend to be expensive relative to the volatility target of the index, which means participation rates are lower. DRC is essentially old technology with lower participation rates, while having with the benefit of a live track record of performance.
S&P 500 Futures Intraday Series
Available at 20%, 35% and 40% in Excess Return, decrements and TCA adjusted
The Futures Intraday series is the modern equivalent to Daily Risk Control in that the index is comprised of only the S&P 500, but volatility is tracked and traded at 7 intervals within the day. The advantage of intraday volatility management is that the volatility of the index will track much closer to the target, which means the options will be more efficiently priced than in a slower mechanism such as Daily Risk Control. All of that trading also creates transactions cost drag, which reduces the performance of the index (in the TCA version) or increases the price of the options (in the non-TCA version). All things considered, intraday volatility is a net benefit in terms of option pricing and upside potential.
S&P 500 Engle Series
Available at 6%, 8%, 10%, 12%, 14%, 15% and 16% in Excess Return
The Engle series from UBS is also a simple S&P 500 and cash construction, but with an intraday volatility control mechanism based on research by Dr. Robert Engle about how realized volatility within an index materializes throughout the trading day. Engle indices also contain a de-risking factor that only affects how the index allocates to the S&P 500 when losses start to pile up. It’s not as simple as Daily Risk Control or Futures Intraday, but it’s not nearly as noisy, complex or backtest-optimized as many of the other indices in the market. Think of it as one click off of pure simplicity. S&P Fast Convergence, which is Bank of America’s proprietary intraday volatility mechanism, is similar to Engle, however, it is only available at two volatility targets (11.5% and 7%).
S&P Dynamic Intraday, Intraday Edge, Advantage, IQ and Volatility Stabilizer
Despite the appearance of simplicity, all these indices layer on additional moving parts to the core methodology. The most common additional feature is a trend-following mechanism that boosts backtested performance but may cause the index to perform materially differently than the underlying index. As a result, they don’t qualify as “pure” volatility control solutions and should be positioned as more opportunistic, return-seeking structures that can underperform in some environments and outperform in others – and without a lot of transparency as to exactly why performance materialized the way it did.